 Revolutionizing · Modernizing · Simplifying
21%.
That is the share of American home buyers over the past year who were buying their first home — and it is the lowest number the National Association of Realtors has ever recorded. A year ago it was 24%. A decade ago it was closer to 40%. First-time buyers are quietly disappearing from the market.
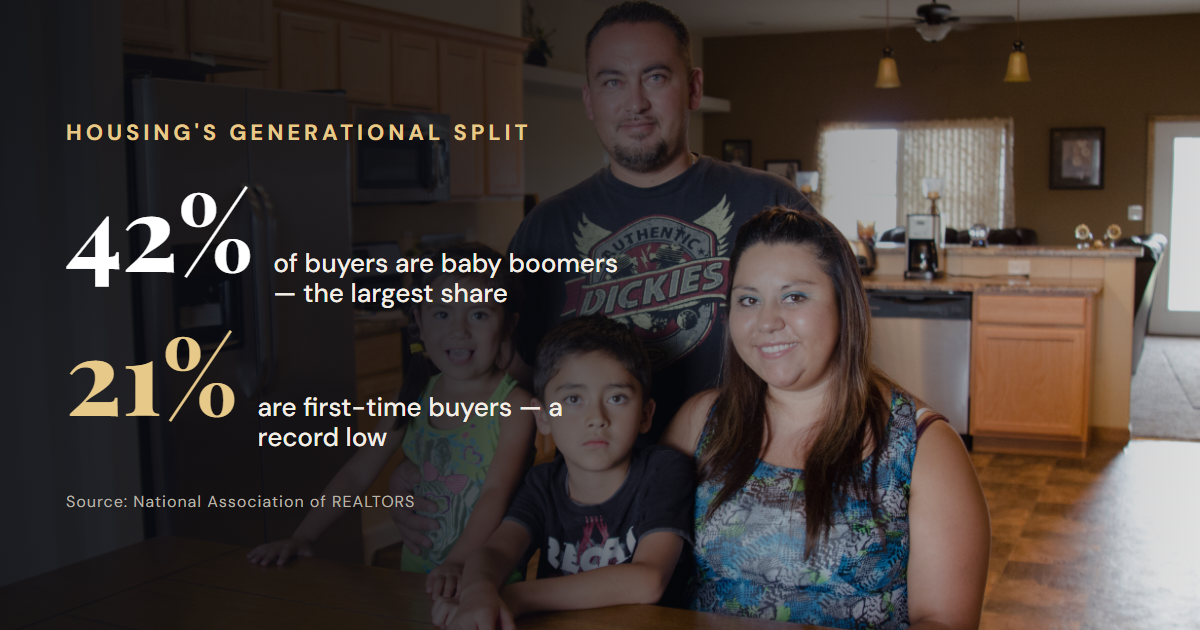
Meanwhile, look at who is actually closing. Baby boomers are now the largest group of buyers in the country at 42% of the market. Millennials — the generation everyone assumes is finally settling down — slipped to 26%. Read that one more time: people in their 60s and 70s are out-buying people in their 30s.
Boomers bought years ago, rode a decade of price growth, and a lot of them own free and clear. When they buy now, they are moving equity around, not begging a bank for a 7% loan. They are also the biggest sellers in the market at 55%, and they tend to sit tight for a long time before they list — a median of 11 years, and 15 for the oldest owners. So they sell one house carrying a mountain of equity and roll it straight into the next. That is a very different starting line than a first-timer standing at the curb with a down payment and a pre-approval.
First-time buyers fell to 21% of the market, down from 24% a year ago. The people it hits hardest are younger Millennials — the exact group that should be forming households and buying starter homes right now. High prices, high rates, and rents that quietly eat the down-payment savings are keeping them renting one more year, and then another.
"The housing market remains sharply divided between homeowners with equity and first-time buyers trying to break in — many of whom are younger Millennials." — Dr. Jessica Lautz, NAR Deputy Chief Economist
With the average Colorado 30-year fixed sitting above 7% this fall and metro Denver prices where they are, the squeeze the national numbers describe is even tighter here. A boomer downsizing out of a paid-off house can bring cash, waive contingencies, and close fast. A first-time buyer saving a down payment at a 7% rate is playing a completely different game on the same field.
That does not mean first-timers are locked out. It means strategy matters more than it ever has — rate buydowns, seller-paid concessions, down-payment assistance, and going after the house nobody else is fighting over. (We broke down one of those builder buydowns earlier this week, along with the year-three catch that comes with it.)
We wanted a real Colorado figure here, not a guess — so here is what the hard data supports.
In 2025, Colorado recorded about 51,400 residential closed sales (40,606 single-family plus 10,794 condo and townhome), according to the Colorado Association of REALTORS. That same year, the Colorado Housing and Finance Authority — CHFA, the state's main first-time-buyer program — financed 5,491 home purchases, and 93% of them went to first-time buyers (roughly 5,100 households).
Run the math and CHFA's first-time buyers alone accounted for about 10% of every home sale in the state — roughly one in ten Colorado closings, through a single program.
And that is only the floor. It does not count the first-timers who used a plain conventional loan, FHA on its own, VA, cash, or any of the other down-payment-assistance programs out there. So Colorado's true first-time-buyer share is comfortably higher than that 10% — we just won't slap a precise number on it that the data can't back up.
Here is the honest read. Nationally, first-time buyers are a record-low 21% of the market. In Colorado, one first-time-buyer program by itself is already carrying about 10% of all sales — which tells you how much of the entry-level market in this state leans on assistance to clear the price-and-rate wall. When homes cost what they cost here, getting a first-timer to the closing table increasingly takes a program, a buydown, or a very deliberate plan. That is exactly the gap a good agent is for.
Through all of it, buyers still lean on a pro. 88% of buyers and 91% of sellers worked with an agent this year, and 91% of buyers said they would use their agent again. In a market this lopsided, knowing which lever to pull is the whole difference between watching and closing.
Whether you are trying to break in for the first time or move up out of a house you have owned for a decade, the playbook is different for each one. Figuring out which one is yours is where this starts.