 Revolutionizing · Modernizing · Simplifying
Eight offers. One house. And it closed sixty-five grand over asking.
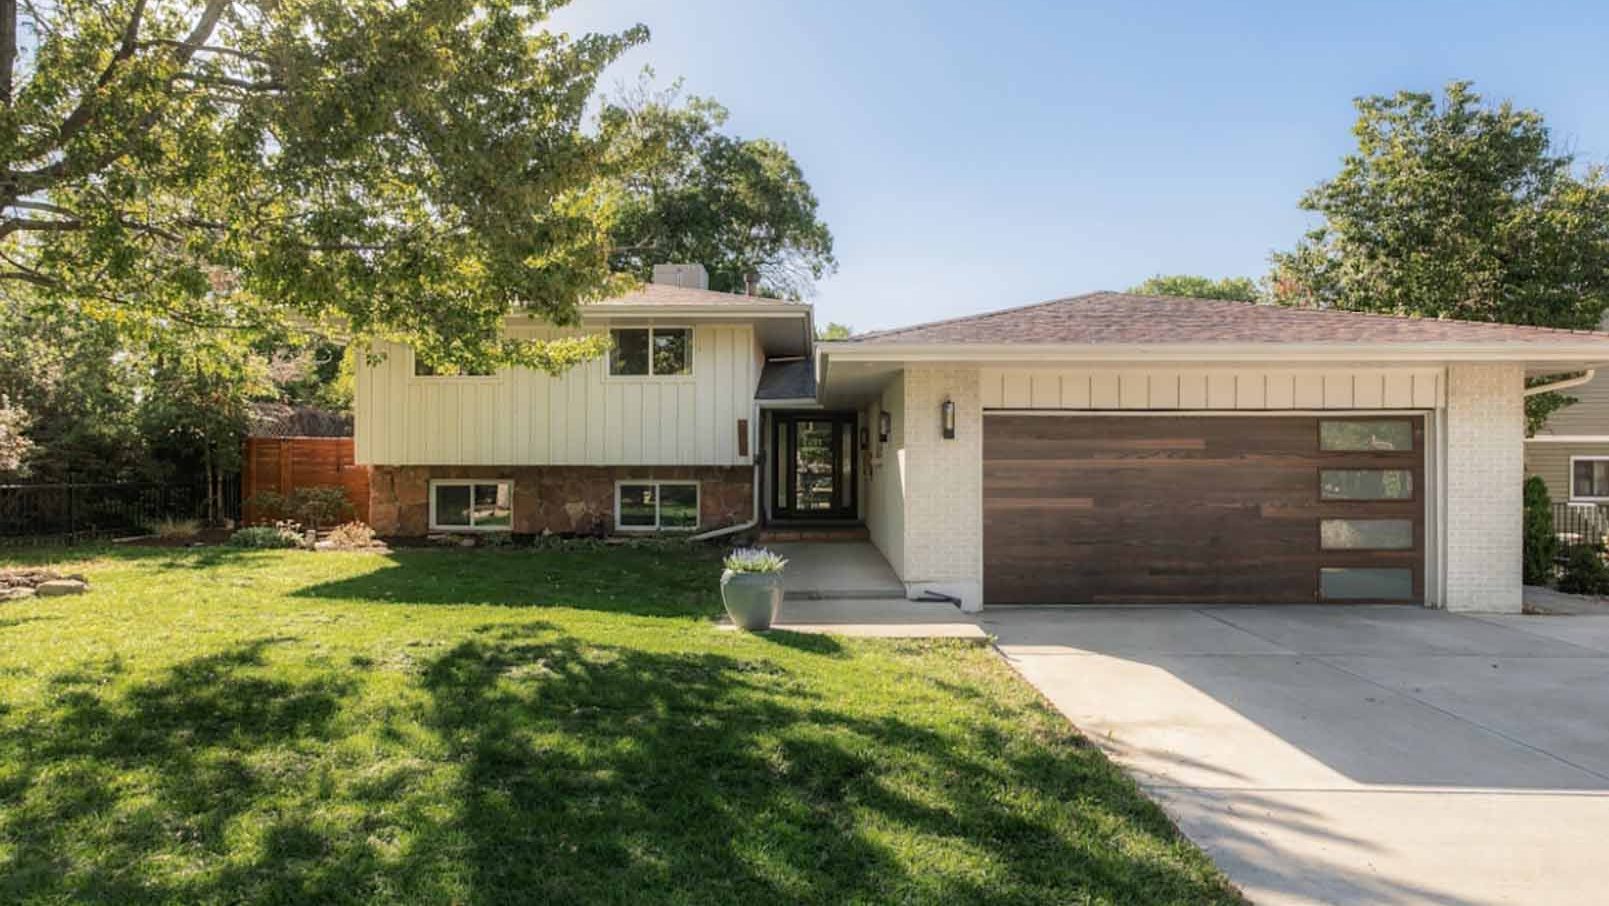
That is what happened at 3441 Fenton Street in Wheat Ridge, 80212, last month. A remodeled white-brick home, four beds, three baths, 2,325 square feet, sitting on a quarter-acre-plus lot right across from Panorama Park. Listed at $850,000. Sold at $915,000. The Denver Gazette ran the numbers on November 5th, and if you only read that one line you would think we are back in 2021.
We are not. And the gap between that Fenton Street result and what most sellers are actually getting right now is the whole story this month. So let me walk you through it.
The October report from the Denver Metro Association of Realtors looks pretty quiet if you squint. The median residential closing price actually went up. It rose 3.48% from September to $595,000, which is also up 0.85% from a year ago. Homes spent a median of 30 days on market, down from 31 in September and 33 last October. Official stats still show homes selling at more than 98% of list price within a month of listing.
Sounds healthy, right?
Here is the thing. Everything underneath that number is softening. Closed sales came in at 2,748 homes in October, down 8.58% from September and a brutal 23.54% from a year ago. Pending sales fell 7.27% month-over-month and 20.34% year-over-year. There were 12,978 active listings at the end of the month. That is 4.34% fewer than September, but still 3.87% more than a year ago. And if you are shopping condos or townhomes, buyers are staring at more than seven months of inventory. That is not a seller's market. That is buyers taking their sweet time.
This is the part people miss. Agents will tell you the 98%-of-list figure masks what is really happening, and the data backs them up.
DMAR's Market Trends chair, Amanda Snitker, said 65% of homes sold in October involved a seller concession. Sixty-five percent. The average concession was
Then there is the price-cut crowd. A First American Title report that went around to Denver-area Realtors this week found that homes going under contract after a reduction took an average cut of $58,381. That is 7.7% off the original list price. Almost sixty thousand dollars. On a home. That does not show up in the median either, because by the time it sells, the 'list price' everyone measures against is already the lowered one.
So you have got two discounts happening at once. The concession at the table, and the price cut before you even get to the table. Both invisible in the headline.
Now back to Wheat Ridge. Why did that house pull eight offers in a market where most sellers are negotiating from behind?
Two reasons, and neither is luck. Condition and price. It was a clean white-brick remodel in a genuinely good 80212 pocket, across from a park, move-in ready. And the listing agent, Kelly Reed, has been pretty direct about the strategy: do the research and price it for a quick sale. Price it right, present it right, and buyers still show up swinging. Underprice a touch, create competition, let the market find the real number. $850,000 became $915,000 because the home gave buyers a reason to fight.
Compare that to the seller who lists high, waits, and then slices $58,000 off eight weeks later while also handing over a concession. Same market. Completely different outcome. That is the lesson homeowners need to sit with right now.
Deviree Vallejo, an agent with a Denver brokerage, put it to the Gazette about as bluntly as it gets: 'some sellers don't get the message, and there is so much on the line for them.' And look, she is right. The money at risk is not theoretical. It is your equity.
If you own something over
One more number worth your attention, because it tells you who is actually walking through these doors. The National Association of Realtors reports the typical first-time homebuyer is now 40 years old. All-time high. The first-time share did tick up to 22% in 2026 from a low of 21% in 2025, so they are coming back, slowly. But these are not twenty-somethings stretching for anything with a roof. These are careful, older, cash-conscious buyers who have waited years and will not overpay for a house that needs work.
Which is exactly why Fenton Street worked and why the stale listing down the street keeps cutting.
So the market is not crashing, and it is not booming. It is sorting. Priced-right-and-move-in-ready gets eight offers. Everything else negotiates. If you are thinking about selling into this, the honest question is not what your neighbor got last spring. It is which of those two houses yours is going to be. We are happy to tell you straight.