 Revolutionizing · Modernizing · Simplifying
Right now, if you are renting in Denver, you are holding the best cards you have held in about ten years. That is not a feeling. That is the math.
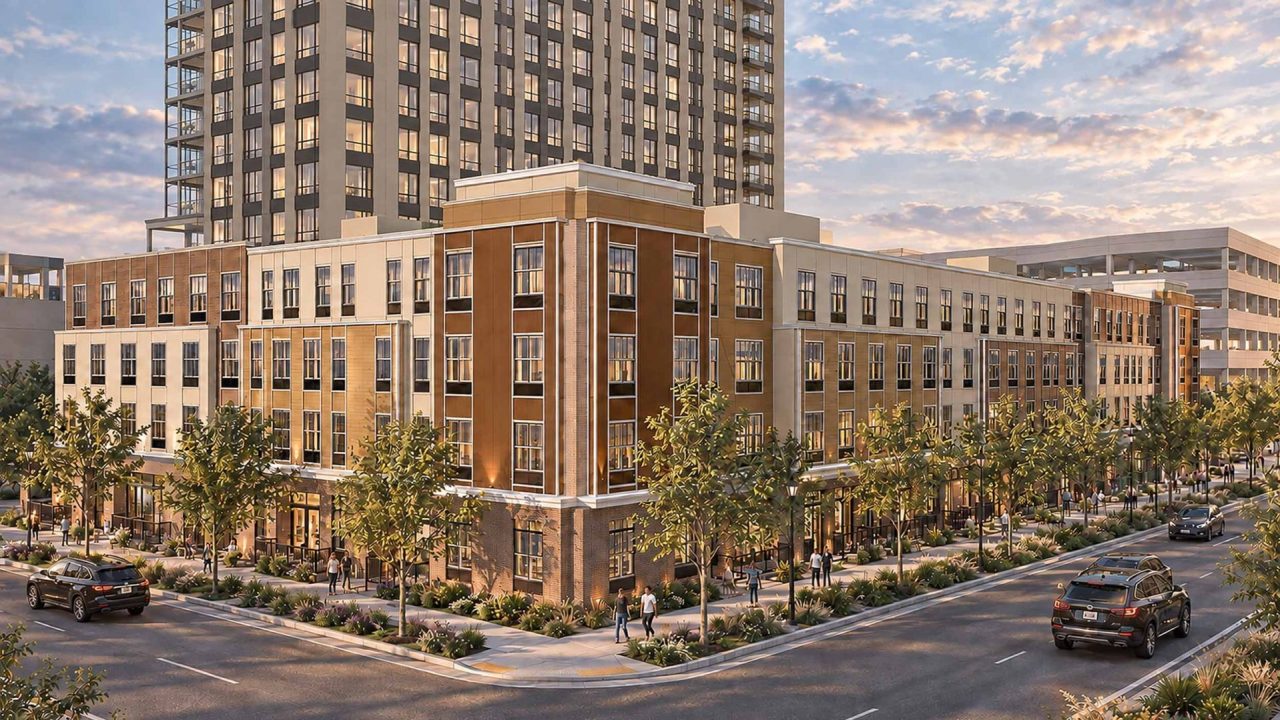
The metro vacancy rate, once you count all the new apartments that have gone up and still have not filled, sits somewhere between 9.4% and 10.9%. That is high. Historically high. Landlords are competing for you, which means concessions, free months, and effective rents getting pushed down across the board. Enjoy it. Because the people who build these buildings for a living are already betting it does not last.
Here is the part people miss. The soft rents are not some natural market mood. They are the hangover from a building spree.
Analyst Zucker pins it on overbuilding over the past four years, and he does not expect it to clear out until into 2028. So all those cranes you watched go up during and after the pandemic? The units landed basically all at once, and the market is still digesting them.
And it gets more interesting. A lot of the new market-rate stuff is now competing head to head with apartments that were originally built for lower-income renters using government tax incentives. When the shiny new building a block over is dangling two months free, the older income-restricted building has to answer. That pressure runs down through every segment, not just the luxury towers. Everybody is discounting to fill units.
But the vacancy picture is not even across the metro, and this is where it matters for you.
The city of Denver itself has the metro's highest stabilized vacancy rate, 7.0%. That is your leverage zone.
Now drive west. Jefferson County, this summer, posted a stabilized vacancy rate of 5.4%, one of the lowest in the whole metro. Same region, completely different renter experience. Tighter, less wiggle room, fewer giveaways.
So what does a developer do when it sees a county that is already tight? It builds. Terre Haute based Thompson Thrift just announced a 284-unit market-rate project on a 9-acre site on South Golden Road at 12th Avenue. That is about two miles south of Golden's historic Lincoln Avenue, the main street everybody knows. These are not amateurs taking a flier. Thompson Thrift has put up around 30,000 units over the past two decades, including 32 projects here in Colorado. When a builder with that track record plants 284 units in the county with the lowest vacancy, that is a read on where the puck is going.
And they are not alone. Over in Denver, Zocalo Community Development is pushing its Liora project, plus an adjoining tower, into a mixed market-rate and below-market development a block from Sloan's Lake Park. A block from the lake. That is prime, and it is going up right into a glut. Which tells you something about the two-year horizon these folks are underwriting.
The theory is simple. Nobody is starting new projects right now because the numbers are ugly, and the stuff already in the pipeline finishes up by 2028. Population keeps coming. Demand keeps building behind the dam. So the people breaking ground today are aiming to deliver right as the oversupply burns off and renters are once again chasing too few units.
That is a timing call. And timing calls are exactly the kind of thing that decides whether you lock a lease, renew, or go buy something.
So maybe you are thinking, fine, I will just buy and skip the whole rent circus. Here is the thing. The door is heavier than it used to be.
Freddie Mac's 30-year fixed averaged 7.40% the week of October 8, up from 6.30% a year earlier. A full point higher. That alone is parking a lot of would-be buyers right back in the rental pool, which, side note, is part of what keeps apartment demand alive even with vacancy this high.
The for-sale side is wobbly too. In the September 2026 reports, metro-wide active listings hit 13,567, up 3.77% year over year, while closed sales fell 21.39%. More homes sitting, fewer people buying. And the median attached price, your condos and townhomes, fell about 6.2% year over year to somewhere around $365,500 to $375,000, depending on whether you read the DMAR numbers or the Colorado Association of REALTORS numbers. So the rental glut and soft condo prices are happening at the same time. That is not a coincidence. That is the same cooling market showing up in two places.
Look, I am not going to tell you what to sign. But here is how I would frame it if Hayley and I were in your shoes.
If you are renting in the city of Denver right now, you have real negotiating power. Push on concessions. A one-year lease might not be where the value is if the builders are right about 2028, because renewing into a tightening market in two years could sting. Out in Jefferson County at 5.4%, do not expect the same generosity.
If you are thinking about buying attached product while prices are down 6%, just run it against a 7.40% rate before you celebrate the discount. The sticker looks better. The monthly might not.
The smart money is betting today's renter's market flips inside two years. That does not mean they are right. It means somebody with 30,000 units of experience is putting money on it. Worth your attention when you decide what to sign.